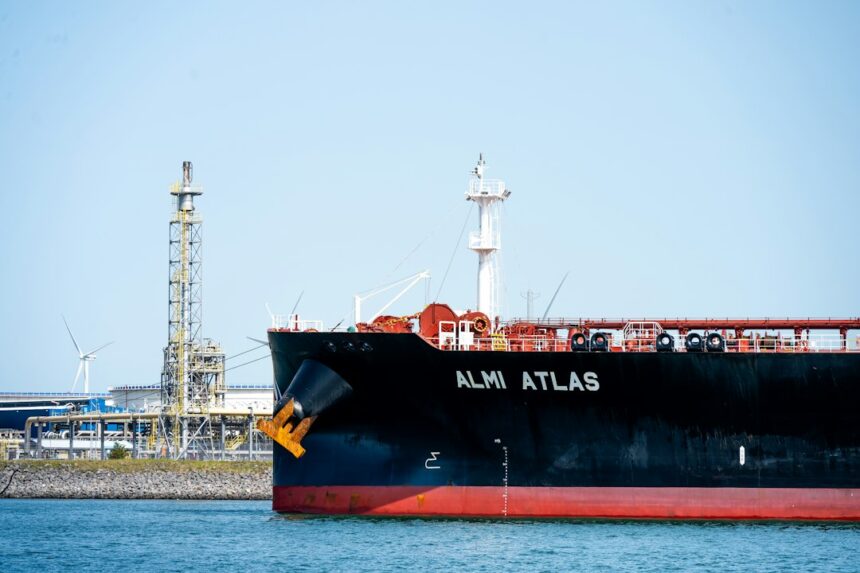
Venezuela’s oil trade is experiencing a significant transformation, driven by recent sanctions adjustments that have reopened trade opportunities. This newly crafted legal framework has not only impacted who is allowed to engage in trade but has also altered the dynamics of vessel operations and risk assessments.
Changes in Export Volumes
According to Kpler flows data, Venezuelan crude oil exports averaged around 870,000 barrels per day (kbd) during 2025. This figure remained steady despite tightening sanctions which altered the legal landscape for trade. A notable drop in exports occurred in January 2026, when volumes fell to approximately 667 kbd, indicative of the complex relationship between sanctions and oil production levels. However, exports rebounded from April to September 2026, averaging about 1.14 million barrels per day as operators adapted to the evolving environment.
Licensing Changes and Market Adaptation
The U.S. sanctions policy has undergone several phases since early 2025. The announcement on 26 February 2025 regarding the wind-down of energy-related authorizations prompted the issuance of general licenses by the Office of Foreign Assets Control (OFAC), allowing certain joint venture activities to continue, albeit under stricter conditions. The issuance of Executive Order 14245 in March 2025 established a discretionary tariff on Venezuelan oil imports, primarily impacting Chinese buyers.
In 2026, particularly after political changes in Venezuela, OFAC swiftly issued multiple general licenses that expanded permitted transactions within the oil and gas sector. This series of license modifications demonstrated a clear shift from broad sanctions pressure to more selective waivers, allowing for a controlled reopening of the oil sector.
Impact on Logistics and Trading Routes
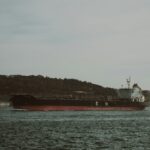
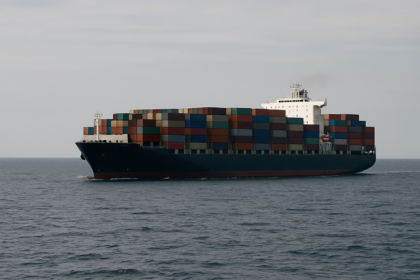
The evolving sanctions have had profound implications for the logistics and trading routes of Venezuelan crude. While in previous years, China and unknown destinations dominated export destinations, the latest data indicates a shift with the United States emerging as the largest identified importer, followed by firms in India and Spain. This trend aligns with the new licensing framework that seeks to channel Venezuelan oil into more traceable commercial corridors.
Despite these developments, the risk associated with trading Venezuelan oil persists. Vessels’ movements can still obscure their ultimate destinations, particularly in regions such as the Bahamas and Curaçao and through ship-to-ship transfers. Consequently, rigorous vessel monitoring and counterparty analysis have become essential components of operational risk management for shipping companies involved in Venezuelan oil transports.
Behind the Headline
The reopening of Venezuelan oil trade highlights the intricate balance between regulatory frameworks and operational realities in the shipping industry. As sanctions evolve, shipping operators face the dual challenge of navigating compliance and understanding the shifting landscape of oil demand and logistics. The importance of scrutinizing vessel movements and cargo origins is paramount, as even permitted trade can entail varying levels of risk. Future developments will likely involve ongoing adjustments to licensing requirements, making adaptive strategies essential for operators moving Venezuelan oil.