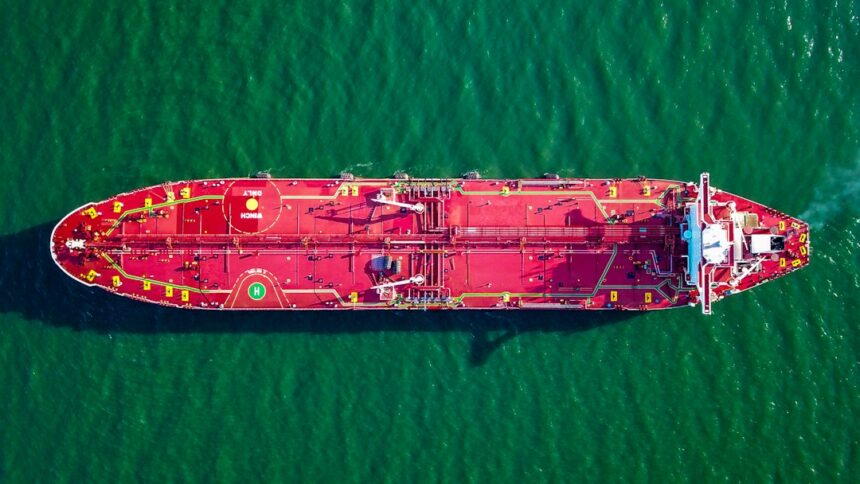
A substantial expansion of the global tanker fleet is on the horizon, with S&P Global Energy CERA estimating tanker capacity to rise from 703.72 million deadweight tons (dwt) at the end of 2025 to 862.98 million dwt by 2029. This 22.6% growth over four years poses potential challenges for the freight market, especially considering recent market conditions driven by geopolitical tensions.
Market Dynamics and Geopolitical Factors
The surge in tanker rates, particularly following the United States-Iran conflict that began at the end of February, has dramatically altered the market landscape. Increased demand from Asian importers and Middle Eastern producers seeking to mitigate risks around critical transit routes—such as the Strait of Hormuz—has led to significant spikes in charter rates. The Global Dirty Tanker Index, which tracks rates for non-scrubber-fitted, non-eco tonnage, saw a jump to $840,921.58/day as of November 2, a staggering increase of over 400% since February 27.
However, as the tanker market transitions from a phase characterized by scarcity to one where supply pressures intensify, analysts warn that sustaining current freight rates could prove challenging. According to the CERA report published on October 28, the real question for operators is whether ton-mile demand, scrapping, and sanctions-related operational inefficiencies can absorb the anticipated increases in supply without triggering a downturn in utilization and freight rates.
Future Growth and Challenges
The delivery schedule for new tankers is poised to contribute markedly to the fleet’s overall size. By the end of September, the order book featured 1,494 tankers, signifying 18.3% of the fleet by count and 25.1% by capacity, primarily dominated by Very Large Crude Carriers (VLCCs) and Suezmaxes, which together account for approximately 70.5% of ordered capacity. Projections indicate that VLCC capacity will increase by 31.5% by 2029, amplifying the competitive environment for existing operators.
Despite a robust freight market, the potential influx of new vessels, particularly during the latter part of the decade, raises concerns about market saturation. CERA analysts underscore that while the current freight boom has led to record valuations for tanker assets—a five-year-old VLCC is now estimated at $185 million—there might soon be too many ships chasing limited demand, particularly if geopolitical conditions stabilize or if sanctions are eased, leading to a normalization of trade.
Behind the Headline
The anticipated growth in tanker fleet size underscores a critical juncture for the shipping industry. Operators must navigate a landscape where rapid capacity expansion could outpace current demand levels, thereby leading to downward pressures on freight rates and utilization. The current volatility in geopolitical events has shielded the market from initial shocks, but operators should remain vigilant about forthcoming deliveries and operational adjustments. They must prepare strategies not just for maximizing current asset values but also for addressing the looming threat of increased effective supply that could reshape the competitive dynamics of the tanker market.