Clarksons Research has announced that the ClarkSea Index, a critical indicator of shipping rates across the market, has achieved an all-time high, averaging $46,384 per day for the third quarter of 2026. This milestone surpasses the previous record of $44,222 per day set in Q2 2008 and marks a doubling of the ten-year trend.
Driving Factors Behind the Surge
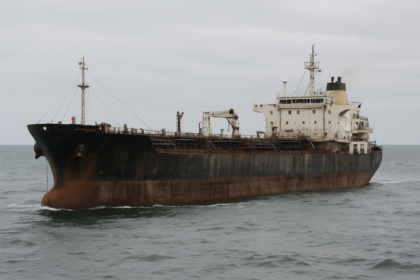
The surge in the ClarkSea Index is primarily attributed to exceptionally high disruption-driven rates in the crude and LPG markets. Notably, Very Large Crude Carriers (VLCCs) have reported average daily earnings of $671,000, with certain routes reaching as high as $1.6 million by early October. This is a significant increase from the previous quarter, driven by a continuous flow of crude through the Strait of Hormuz, which has seen varying volumes from an estimated 12 million barrels per day (bpd) during the last quarter, down from pre-conflict levels of 15 million bpd.
Key logistical changes have also played a role, as shuttling operations in the Middle East Gulf have redirected oil to the Gulf of Oman for transfer to additional tankers bound for Asian markets. Furthermore, logistical adjustments at Yanbu have re-routed flows to Asia to minimize risk from the Houthi threat, opting for supply via the SUMED pipeline and the Cape of Good Hope.
Market Conditions and Future Outlook
The overall market for newbuild orders signals ongoing strength, with the orderbook backlog increasing by 25% year-on-year in compensated gross tonnage (CGT) terms. The crude tankers’ segment has seen prices reach record levels, indicating a robust interest in asset acquisition, with 15-year-old VLCCs reportedly priced above newbuild costs.
Despite these promising developments, operational risks remain elevated, with over 100 vessel attacks reported in the Gulf and at least ten incidents in the Red Sea this year. Broader geopolitical tensions, including ongoing sanctions against Russia, tariffs, and restrictions in Panama, continue to shape shipping dynamics. As the global economy faces resilience and building risks, stakeholders must closely monitor how normalization may unfold in the coming year.
Behind the Headline
The record levels of the ClarkSea Index underline the current complexities facing shipping operators and charterers. With VLCCs and other vessel classes commanding unprecedented rates, operators are pressured to adapt to evolving geopolitical landscapes and market demands. The logistics shifts observed, particularly with shuttling strategies, highlight the need for flexibility in shipping operations. Furthermore, as asset prices soar, the implications for financing and investment strategies become critical. Future developments will demand careful navigation of operational risks as tensions continue to affect global shipping lanes.