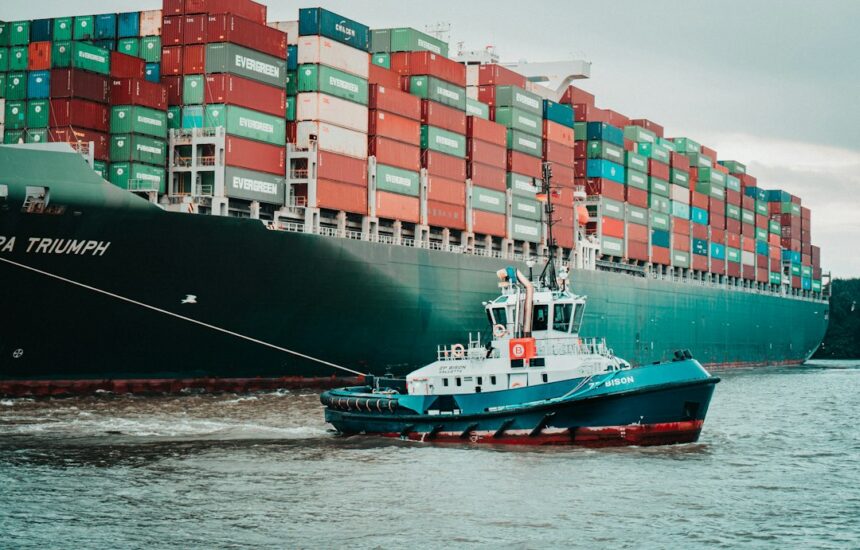
The UK Emissions Trading Scheme (UK ETS) officially extended its reach to domestic maritime activity on 1 July 2026. This initiative follows similar frameworks seen in the EU ETS and the upcoming regulations under FuelEU Maritime. The implementation marks a critical moment for maritime operators, especially charterers, who must navigate the complexities of maintaining compliance under both UK and EU emissions regulations.
Scope of the UK ETS
Under the UK ETS, vessels of 5,000 gross tonnage (GT) and above are subject to emissions regulations during voyages between UK ports and related port activities. Importantly, the scheme only covers emissions generated within UK ports, meaning that for international voyages, only UK port emissions are liable for compliance. Domestic UK voyages and activities at UK ports will require a full 100% surrender of allowances, while voyages to Northern Ireland will have a 50% surrender deduction applied. Specific emissions such as CO2, methane (CH4), and nitrous oxide (N2O) are monitored on a tank-to-wake basis, necessitating thorough documentation and reporting from maritime operators.
Liability and Responsibility
The regulatory burden primarily falls upon the maritime operator, typically the registered shipowner. However, should the registered owner not fulfill the roles of an International Safety Management (ISM) company, responsibilities may shift to the ISM company through a legally binding agreement. Importantly, the operational status of a charterer does not automatically equate to operator liability merely due to the financial responsibility for emissions allowances. Instead, clarity within the charter party is essential to delineate the level of responsibility and potential liabilities. In scenarios where the charterparty does not explicitly allocate the costs for allowances, the owner is at risk of non-compliance with regulatory authorities.
Navigating Combined Regulations
Charterers must remain vigilant of the distinctions between UK allowances (UKAs) and European Union allowances (EUAs), as compliance systems are not interchangeable. The EU ETS continues to apply broader regulations covering intra-EEA emissions, adding complexity to the operational planning of charterers servicing both regions. Each regime requires precise accounting and distinct compliance costs, underscoring the importance of robust contractual clauses in chartering agreements. The BIMCO ETS Allowances Clause for Time Charter Parties provides a template for the allocation of emissions-related costs, ensuring that owners monitor and report emissions while charterers handle the allowance settlements.
Behind the Headline
The UK ETS’s expansion into maritime operations introduces a new layer of complexity for vessel owners and charterers alike. As emissions trading schemes develop, industry stakeholders must prepare for increased scrutiny and manage both operational practices and financial obligations effectively. Ongoing dialogues concerning emissions regulations will likely influence shipping costs and operational efficiencies, compelling charterers to adopt thorough compliance strategies that encompass both domestic and international requirements. Close attention to charterparty language, particularly regarding emissions allowances, is imperative for mitigating potential liabilities in future contracts.