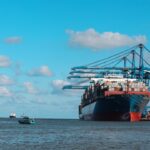
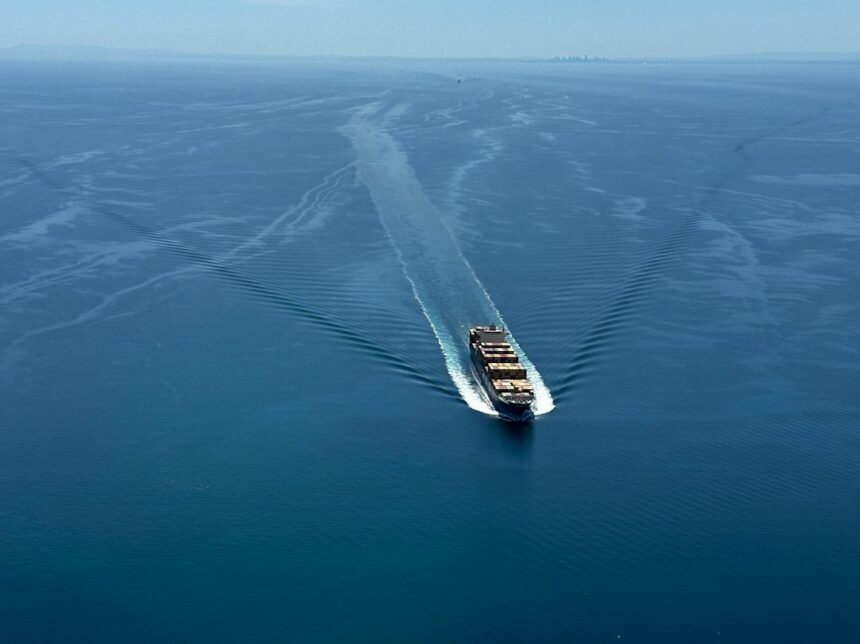
A surge in ship prices has been observed as demand for new vessels continues to rise amidst a decreasing availability of tonnage. In its latest report, shipbroker Banchero Costa noted a continued flow of newbuilding orders across various sectors, indicating a positive market environment for shipbuilders.
New Orders Indicate Strong Market Demand
In the dry bulk sector, Yangzijiang Maritime of China has confirmed an order for six 64,500 deadweight ton (dwt) bulk carriers from Jingjiang Nanyang, with the projected delivery set for March 2029. Each vessel is estimated at around USD 35 million. Additionally, South Korean shipowner HMM has placed an order for eight 210,000 dwt ore carriers with Yangzijiang Shipbuilding, which are priced approximately at USD 105 million each and are backed by long-term contracts with Brazilian mining giant Vale.
Moreover, Fujian Shipping Group has also ordered two 82,000 dwt bulk carriers at Jiangsu Haitong Offshore Engineering for about USD 41.2 million each, with a delivery expected in May 2028. The ongoing interest in modern, efficient designs underscores a shift towards more environmentally friendly technologies across the industry.
Trends in the Second-Hand Market
In the sale and purchase (S&P) market, activity spanned all major dry bulk size segments. The Newcastlemax sector attracted significant attention, with ships like the “Houheng 6” and “Houheng 5” selling for over USD 70 million each. On the Capesize front, the “Highland” was sold for over USD 25 million, while Kamsarmax and Panamax vessels changed hands in the range of USD 22 million and USD 13 million, respectively. This variety in transactions reflects a healthy trading environment for ship operators.
Tanker sales also demonstrated robust activity, with the “Sea Leopard,” a 314,000 dwt VLCC, fetching USD 135 million. Other notable transactions included the “Montestena” on the Suezmax segment, sold for USD 87 million, and several smaller products and Aframax tankers also changing hands at competitive prices.
Implications for Shipbuilders and Operators
The escalation in newbuilding orders and secondary market transactions is indicative of a shifting maritime landscape. With long-term contracts, particularly in the dry bulk and mining sectors, shipbuilders are positioned favorably. Operators are also seeing an opportunity to modernize fleets with dual-fuel and efficient designs, responding to regulatory pressures and environmental considerations.
As demand persists, the interplay between fleet modernization and availability will likely impact global shipping costs and service capabilities moving forward. Stakeholders should monitor this trend closely as it unfolds in the coming months.
Behind the Headline
The current uptick in ship prices and the influx of newbuilding contracts reflect both operational realities and long-term strategic planning within the maritime industry. The demand for tonnage continues to outpace supply, compelling operators to invest in future capabilities while navigating the complexities of an evolving regulatory environment. As operators secure long-term contracts, particularly in resource-heavy sectors, the focus on efficient vessel designs and sustainable practices will shape the maritime market. Observers should watch for further fluctuations in ship prices, which may indicate broader economic trends affecting global shipping.